A home appraisal helps confirm a property's market value. Learn what appraisers review, how value affects your mortgage, and how to prepare with confidence.
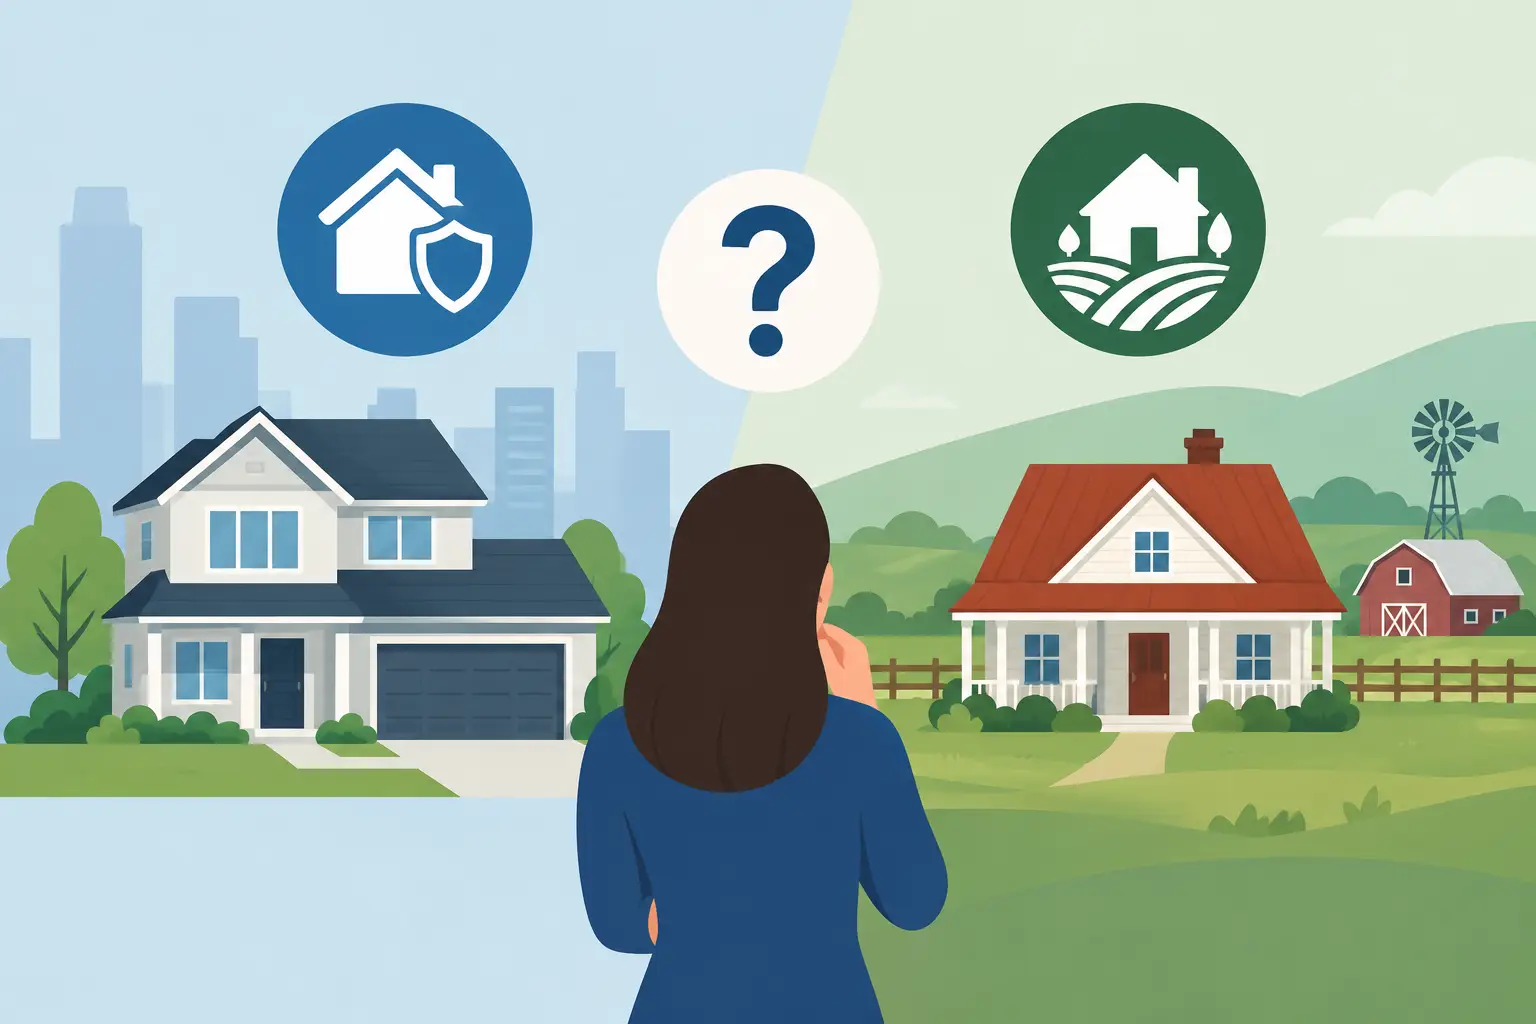
FHA Loan Versus USDA Loan: Which Fits You?
A home that seems affordable on paper can feel out of reach once the down payment enters the conversation. That is why comparing an FHA loan versus USDA loan matters for many first-time and budget-conscious buyers. Both programs can make homeownership more accessible than many conventional loans, but they solve different problems. One may work almost anywhere, while the other can offer zero-down financing in eligible communities.
The best choice is not simply the loan with the lowest advertised rate or smallest cash requirement. It is the loan that fits your income, the property you want, your long-term plans, and the monthly payment you can comfortably carry.
FHA Loan Versus USDA Loan at a Glance
FHA and USDA loans are government-backed mortgage programs, but they are backed by different agencies and built for different types of borrowers. FHA loans are insured by the Federal Housing Administration. USDA loans are guaranteed through the U.S. Department of Agriculture’s Rural Development program.
An FHA loan is widely available for primary residences and is often a practical option for buyers who need flexible credit guidelines or have a modest down payment. A USDA loan is designed for buyers purchasing a primary residence in an eligible rural or suburban area who meet household income limits.
The most noticeable difference is the down payment. FHA financing generally requires at least 3.5% down for borrowers with qualifying credit scores, while USDA financing may require no down payment at all. That does not automatically make USDA the better value. Eligibility requirements, mortgage insurance costs, interest rates, and property location all deserve a close look.
Down Payment and Upfront Costs
For a buyer with a limited amount saved, both loan programs can reduce the upfront barrier to buying a home.
With an FHA loan, borrowers with a credit score of 580 or higher may qualify with a 3.5% down payment. Borrowers with lower scores may need 10% down, subject to lender requirements. FHA also charges an upfront mortgage insurance premium, generally 1.75% of the base loan amount. Many buyers choose to finance that cost into the mortgage rather than pay it in cash at closing.
USDA loans can offer 100% financing, meaning no down payment is required for an eligible buyer and property. USDA loans also have an upfront guarantee fee, which can usually be financed into the loan amount. The fee is typically lower than FHA’s upfront mortgage insurance premium, although program fees can change.
Zero down does not mean zero cash to close. Buyers may still need funds for an appraisal, inspection, earnest money, prepaid taxes and insurance, or other closing costs. In some transactions, seller concessions or lender credits may help with certain costs, but that depends on the loan terms and the purchase agreement.
A quick example
On a $250,000 home, an FHA borrower making the minimum 3.5% down payment would contribute $8,750 before considering closing costs. An eligible USDA borrower might put no money down, preserving savings for moving expenses, repairs, or an emergency reserve. If the USDA home is farther from work, however, higher commuting costs could offset part of that advantage over time.
Credit and Income Rules Are Different
FHA loans are known for flexible credit standards. The program allows borrowers with credit histories that may not meet conventional underwriting expectations, provided they can document stable income, sufficient ability to repay, and responsible recent payment behavior. Individual lender requirements can be stricter than the program minimums, so a credit score alone never tells the whole story.
USDA loans also offer flexible credit opportunities, but income eligibility is a defining requirement. To qualify, household income generally cannot exceed 115% of the area median income. USDA considers the income of household members, not only the people listed on the mortgage application. This can surprise a buyer whose adult child, parent, or other family member lives in the home and earns income.
FHA does not have USDA-style household income limits. If you earn too much for USDA financing, FHA may remain available as long as you meet the lender’s underwriting and debt-to-income requirements.
This distinction matters for growing families and multigenerational households. A USDA loan may be a strong fit for one buyer but unavailable to another purchasing the same property simply because of total household income.
Where You Buy Can Decide the Answer
FHA loans can be used to purchase an eligible primary residence in cities, suburbs, small towns, and rural communities. The property must meet FHA appraisal and safety standards, but the program does not restrict buyers to designated geographic zones.
USDA loans require the home to be in a USDA-eligible area. Despite the term “rural,” many eligible locations are not remote farmland. Smaller communities, towns, and suburban areas outside major metropolitan centers may qualify. Eligibility is determined by the property’s exact address, not by a buyer’s general impression of the neighborhood.
USDA homes must also be modest, owner-occupied primary residences. The program is not intended for vacation homes, investment properties, or income-producing farms. FHA loans are also intended for primary residences, although FHA has different rules that can apply to certain multi-unit properties when the borrower occupies one unit.
If you have already found a home in an urban neighborhood, the FHA-versus-USDA decision may be settled quickly because USDA financing may not be available there. If you are still searching in an eligible area, both options may deserve consideration.
Monthly Mortgage Insurance and Long-Term Cost
The lowest down payment is only one part of affordability. Monthly mortgage insurance can have a meaningful effect on your payment and total borrowing cost.
FHA loans require an annual mortgage insurance premium, paid monthly as part of the mortgage payment. The amount depends on factors such as the loan term, loan amount, and loan-to-value ratio. For many borrowers making the minimum down payment, FHA mortgage insurance remains for the life of the loan unless the borrower later refinances into another mortgage type. Borrowers who make a larger down payment may have mortgage insurance removed after a set period under current FHA rules.
USDA loans also include an annual fee, paid monthly, in addition to the upfront guarantee fee. USDA’s annual fee is often lower than FHA’s annual mortgage insurance rate, which can create a lower monthly payment for an otherwise similar loan. But the comparison still depends on the interest rate offered, the loan amount, taxes, homeowners insurance, and how long you expect to keep the mortgage.
A trusted loan officer can prepare side-by-side scenarios using the actual home price, estimated taxes, and current program terms. That is more useful than comparing loan programs in the abstract, especially when a difference of $50 or $100 per month affects your household budget.
Property Standards and Appraisals
Both programs require an appraisal, and both expect the property to be safe, sound, and suitable for year-round occupancy. FHA appraisals are particularly well known for minimum property standards. Peeling paint in older homes, missing handrails, damaged roofs, or safety hazards may need to be addressed before closing.
USDA also has property condition requirements, and the appraisal must support the value and confirm the home meets program standards. Neither loan is designed to finance a home with substantial repair needs in its current condition. Buyers considering a fixer-upper may need to explore renovation financing or negotiate repairs with the seller.
These requirements should not discourage buyers from using FHA or USDA financing. They are meant to protect the borrower and the lender from financing a home with serious condition concerns. Still, it is wise to include a professional home inspection in your purchase process. An appraisal is not a substitute for a detailed inspection.
When an FHA Loan May Make More Sense
FHA may be the better path when you are buying in a city or non-eligible area, when your household income exceeds USDA limits, or when you need the program’s flexible credit structure. It can also be a useful choice for buyers seeking a primary residence with one to four units, provided they meet occupancy requirements.
FHA can be especially valuable if the location of the home matters more than avoiding a down payment. A home close to work, family, schools, or transit may support your finances and quality of life even if it requires a modest upfront investment.
When a USDA Loan May Make More Sense
USDA can be compelling when you have steady income within program limits, are buying in an eligible area, and want to conserve savings by purchasing with no down payment. The lower annual fee may also make the monthly payment more manageable than an FHA option for some qualified borrowers.
It is often an excellent program for buyers who assume they need years more savings before they can purchase. If the property and income requirements line up, the path to homeownership may be closer than expected.
The right mortgage should give you confidence, not leave you guessing about hidden trade-offs. Before making an offer, ask for personalized FHA and USDA payment scenarios based on the homes you are seriously considering. A Red Tree Mortgage loan officer can help you weigh the numbers, verify program eligibility, and choose a financing path that respects both your goals and your budget.

Related Posts